Guide
Water damage insurance basics in California
This is general information from the state's own consumer guides. It is not advice and not a coverage opinion.
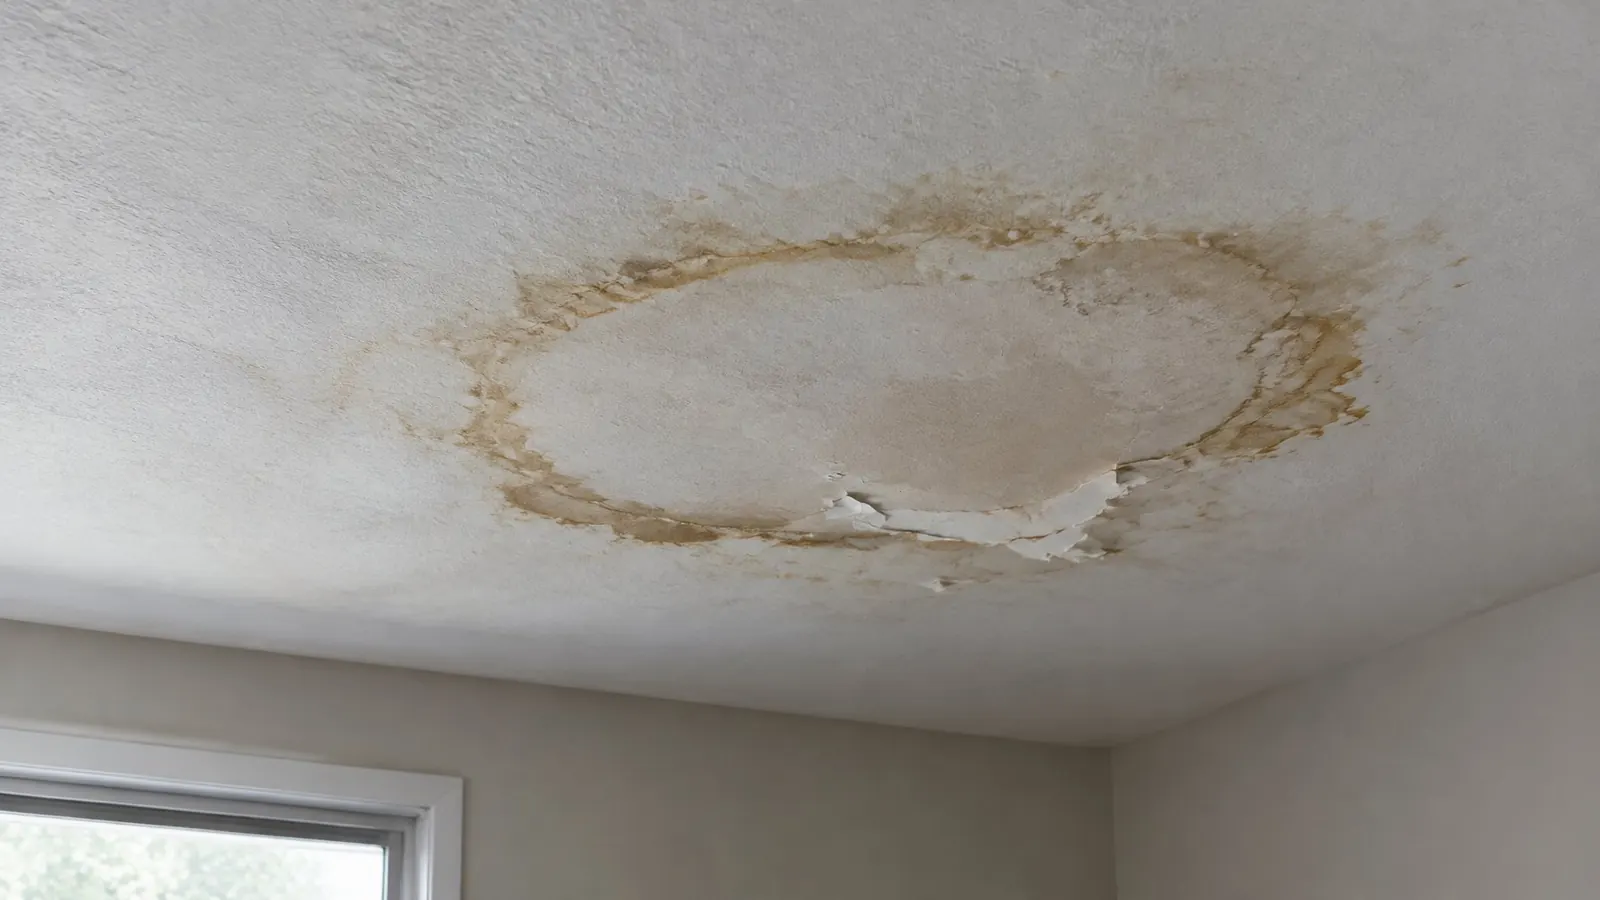
How policies often treat common cases
- Sudden and accidental
- Policies often cover a sudden release of water, but your own policy wording decides.
- Seepage and leaks over time
- Policies often limit or exclude these. Ask your insurer how yours reads.
- Flood
- Homeowners policies do not cover flood. It is available as a separate policy.
- Rain through a storm-made opening
- Often covered when a covered peril such as wind caused the opening.
- Mold
- May be covered when a covered peril caused it. Contact the adjuster before cleanup.
Sewer backup
Some policies treat sewer or drain backup separately, often through an add-on called an endorsement. Read the declarations page for one, and ask the agent to point to the wording.
This site cannot tell you whether yours has one.
Duties after a loss
The department's guide asks homeowners to report the loss promptly, make reasonable temporary repairs, keep receipts and log calls. It adds that policies may not cover ensuing damage when reasonable steps are skipped.
It also advises holding off on extensive permanent repairs until the adjuster has inspected.
Water is still moving, or the room is already wet?
Call the number and describe what happened. You are connected with an independent restoration contractor who serves your ZIP. Calling early helps, because wet drywall and flooring get harder to save each day.